
Weekly Investment Insights
Fed Rate Hike Risk Grows as Equity Complacency Builds
Key Takeaways:
- Global equities debunk historical seasonal trend.
- Fed Chairman warns that inflation is not meaningfully improving.
- Investors pile back into anything AI-related.
- Bonds rally despite a hawkish Fed.
- Commodities gain as yields drop and weather impacts grains.
August Market Recap – August Rewrites the Seasonal Script
August is on pace to break from its historical pattern of weak seasonal returns and delivered a strong month for equity investors. The rally has been broad based with the MSCI AC World Index making its 35th record high for the year and all the major global equity indices that we monitor in positive territory thus far. Equities have benefitted from the best U.S. earnings season since 2Q21, no major upside surprises in inflation, strong manufacturing and the ongoing excitement about AI spending. In this weekly insights we offer an early review from an economic and asset class perspective.
- Warsh leans hawkish: At the annual Jackson Hole Symosium, Fed Chairman Kevin Warsh, took a hawkish tone. He reiterated the Fed’s predominant focus is on prices and underlying trends are not improving enough.
- Labor market: The U.S. economy lost jobs (-23K) for the first time in five months. However, the unemployment rate dipped lower (to 4.1%) as the labor force declined. In addition, wage growth moderated (+3.2% vs. +3.4% YoY).
- Inflation not good enough: The drop in energy prices helped tame the growth in headline prices for the month. However, the Fed’s preferred inflation gauge (PCE Core YoY) is growing 3.3% (YoY).
- Consumer pulls back: Retail sales declined for the month despite relief in gasoline prices. The sharp decline in internet sales may be due to Amazon Prime Day a month earlier this year than last year.
Global Equities: Broadened Rally. As of today, the MSCI AC World Index has rallied with all the major regions posting positive performance. A rotation to the AI trade boosted select emerging markets and U.S. tech the most.
- Emerging markets tied to AI outperform: The MSCI EM Index has been driven higher by Korea and Taiwan as investors move back into semiconductor names.
- U.S. growth over value: The resumption of the AI trade has helped growth stocks outperform value at all three market cap levels. The NASDAQ is on pace for its best performance in three months.
- EAFE lagging: The MSCI EAFE Index is positive but is lagging its international counterparts due to its lack of AI exposure.
Fixed income: Despite hawkish Fed bonds rally. The Bloomberg Aggregate Index is on pace to rally in August after a disappointing July.
- Credit benefits from risk-on sentiment: High yield and emerging market bonds are leading the gains in fixed income.
- Long bonds like muted inflation: The 30YR Treasury bond is rebounding after its worst one-month decline in 19 months in July.
Commodities: Lower yields and weather impact commodities. The Bloomberg Commodity Index is on pace to rally for the second month.
-
- Precious metals lead: Gold is on pace to post its best monthly gain since January as yields dropped and the dollar rose.
- Grains rally: Grains are higher due to adverse weather conditions and ongoing shipping disruptions, which are pushing wheat and corn higher.
LISTEN NOW: Markets With Megan
Your Economic and Market Detailed Recaps
- Home prices are on the rise.
- Consumer confidence slips on inflation fears.
- Fed’s preferred inflation gauge, not good enough.
- Global equities higher, led by U.S. tech.
- Bond yields decline as Fed assures, they will control inflation.
- Commodities drop as gold falls on hawkish Fed.
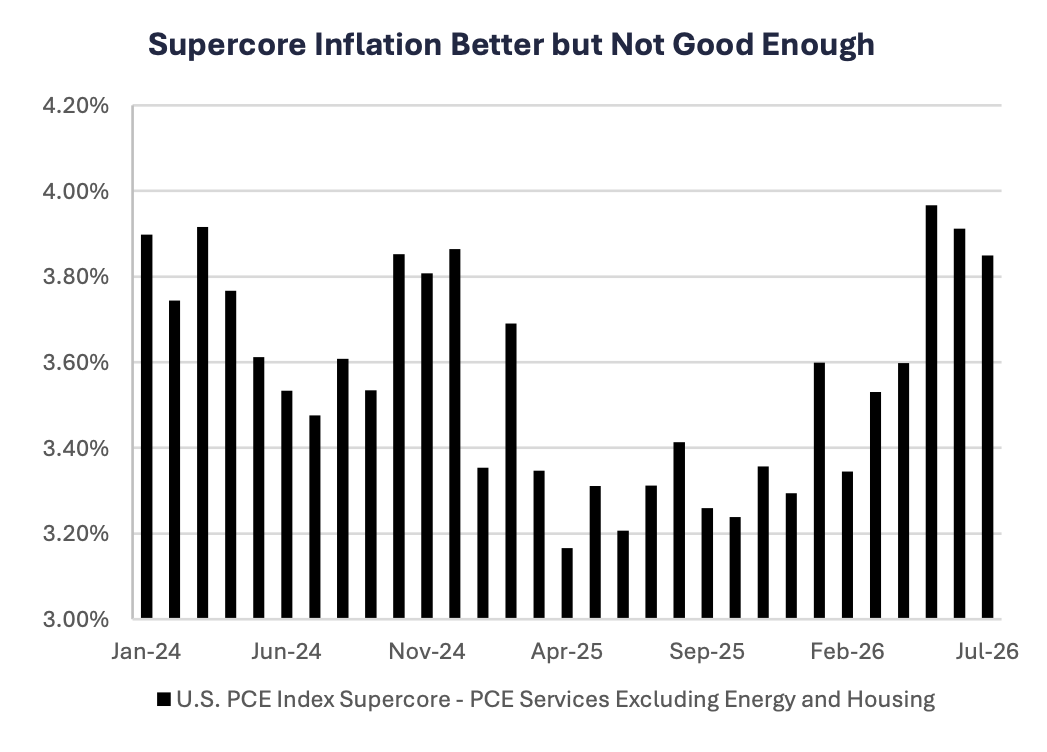
Weekly Economic Recap — Inflation Better but Not Good Enough
Home prices as measured by the S&P Cotality CS Index rose slightly more than expected (+0.24% MoM vs 0.10% MoM) in June. The largest increase was seen in New York, Cleveland and Chicago. The cities that saw price declines were Las Vegas, San Francisco, Phoenix, San Diego and Seattle.
New home sales fell much more than expected in July (-10.5% MoM vs. -1.4% MoM) to a six month low. The biggest drop was seen in the midwest, which fell to the lowest level since 2012. The northeast saw the largest increase for the month (+30% MoM). The months’ supply of homes rose to the highest level seen since January.
Consumer confidence as measured by the Conference Board declined in August but it was led by confidence in the future. The current expectations component fell to a seven month low. While consumers view jobs as plentiful at this time, they remain concerned about inflation in the future.
The second reading on 2Q26 GDP showed economic growth remained at 1.5% (QoQ). However, there was a modest uptick to personal consumption with a decline in private investment in real estate.
The Fed’s preferred inflation indicator (PCE Core YoY) rose 3.3%, well above the 2% target in July. The supercore component which includes services but excludes energy and housing is rising ~4.0% on a year over year basis.
Weekly Market Recap — Global Equities Higher Despite Hawkish Fed
Equities: The MSCI AC World Index was higher for the fourth time in the past five weeks despite Fed Chairman Kevin Warsh not ruling out rate hikes in September. The U.S. led the global returns. Within the U.S. the gains were led by large cap, specifically tech stocks. Small and midcap stocks declined as the chance of a September rate hike increased.
Fixed Income: The Bloomberg Aggregate Index was modestly higher last week as long-term yields fell after Kevin Warsh reiterated that controlling inflation is a priority. Investment grade, high yield and EM bonds led.
Commodities/FX:The Bloomberg Commodity Index fell for the first time in three weeks. The decline was due to a sharp drop in gold prices and Warsh did not rule out higher rates in September. Grains continued to rally on drought conditions in the Plains.
WATCH NOW: Alternate View Podcast
Data is as of July, 2026.
Source: FactSet Research Systems, Verdence Capital Advisors
